Cost-allocation
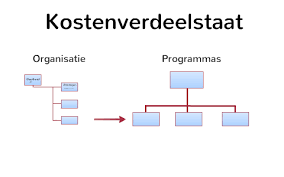
“Cost allocation is the process of identifying, aggregating, and assigning costs to cost objects. A cost object is any activity or item for which you want to separately measure costs. Examples of cost objects are a product, a research project, a customer, a sales region, and a department.”
Ronde 3 (A5)
An overview of the direct and indirect costs and how they are distributed.


“Indirect costs are costs used by multiple activities, and which cannot therefore be assigned to specific cost objects. Examples of cost objects are products, services, geographical regions, distribution channels, and customers”.
The total indirect costs are 2.846.323,78 €
Sale Prices Round 3 (A group)
“Compared to the competition, our prices are balanced and our relatively low production costs allow us to enjoy high profit margins.”